




-
 Agriculture
-
 Health-Care
-
 Environment
-
 Construction-Real-Estate
-
 Tools-Hardware
-
 Home-Garden
-
 Furniture
-
 Luggage-Bags-Cases
-
 Medical-devices-Supplies
-
 Gifts-Crafts
-
 Sports-Entertainment
-
 Food-Beverage
-
 Vehicles-Transportation
-
 Power-Transmission
-
 Material-Handling
-
 Renewable-Energy
-
 Safety
-
 Testing-Instrument-Equipment
-
 Construction-Building-Machinery
-
 Pet-Supplies
-
 Personal-Care-Household-Cleaning
-
 Vehicle-Accessories-Electronics-Tools
-
 School-Office-Supplies
-
 Packaging-Printing
-
 Mother-Kids-Toys
-
 Business-Services
-
 Commercial-Equipment-Machinery
-
 Apparel-Accessories
-
 Security
-
 Shoes-Accessories
-
 Vehicle-Parts-Accessories
-
 Jewelry-Eyewear-Watches-Accessories
-
 Lights-Lighting
-
 Fabric-Textile-Raw-Material
-
 Fabrication-Services
-
 Industrial-Machinery
-
 Consumer-Electronics
-
 Electrical-Equipment-Supplies
-
 Electronic-Components-Accessories-Telecommunications
-
 Home-Appliances
-
 Beauty
-
 Chemicals
-
 Rubber-Plastics
-
 Metals-Alloys
































- Masonry Materials
- Curtain Walls & Accessories
- Earthwork Products
- Fireproofing Materials
- Heat Insulation Materials
- Plastic Building Materials
- Building Boards
- Soundproofing Materials
- Timber
- Waterproofing Materials
- Balustrades & Handrails
- Bathroom & Kitchen
- Flooring & Accessories
- Tiles & Accessories
- Door, Window & Accessories
- Fireplaces & Stoves
- Floor Heating Systems & Parts
- Stairs & Stair Parts
- Ceilings
- Elevators & Escalators
- Stone
- Countertops, Vanity Tops & Table Tops
- Mosaics
- Metal Building Materials
- Multifunctional Materials
- Ladders & Scaffoldings
- Mouldings
- Corner Guards
- Decorative Films
- Formwork
- Building & Industrial Glass
- Other Construction & Real Estate
- Wallpapers/Wall panels
- HVAC System & Parts
- Outdoor Facilities
- Prefabricated Buildings
- Festive & Party Supplies
- Bathroom Products
- Household Sundries
- Rain Gear
- Garden Supplies
- Household Cleaning Tools & Accessories
- Lighters & Smoking Accessories
- Home Storage & Organization
- Household Scales
- Smart Home Improvement
- Home Textiles
- Kitchenware
- Drinkware & Accessories
- Dinnerware, Coffee & Wine
- Home Decor
- Golf
- Fitness & Body Building
- Amusement Park Facilities
- Billiards, Board Game,Coin Operated Games
- Musical Instruments
- Outdoor Affordable Luxury Sports
- Camping & Hiking
- Fishing
- Sports Safety&Rehabilitation
- Ball Sports Equipments
- Water Sports
- Winter Sports
- Luxury Travel Equipments
- Sports Shoes, Bags & Accessories
- Cycling
- Other Sports & Entertainment Products
- Artificial Grass&Sports Flooring&Sports Court Equipment
- Scooters
- Food Ingredients
- Honey & Honey Products
- Snacks
- Nuts & Kernels
- Seafood
- Plant & Animal Oil
- Beverages
- Fruit & Vegetable Products
- Frog & Escargot
- Bean Products
- Egg Products
- Dairy Products
- Seasonings & Condiments
- Canned Food
- Instant Food
- Baked Goods
- Other Food & Beverage
- Meat & Poultry
- Confectionery
- Grain Products
- Feminie Care
- Hair Care & Styling
- Body Care
- Hands & Feet Care
- Hygiene Products
- Men's Grooming
- Laundry Cleaning Supplies
- Travel Size & Gift Sets
- Room Deodorizers
- Other Personal Care Products
- Pest Control Products
- Special Household Cleaning
- Floor Cleaning
- Kitchen & Bathroom Cleaning
- Oral Care
- Bath Supplies
- Yellow Pages
- Correction Supplies
- Office Binding Supplies
- Office Cutting Supplies
- Board Erasers
- Office Adhesives & Tapes
- Education Supplies
- Pencil Cases & Bags
- Notebooks & Writing Pads
- File Folder Accessories
- Calendars
- Writing Accessories
- Commercial Office Supplies
- Pencil Sharpeners
- Pens
- Letter Pad/Paper
- Paper Envelopes
- Desk Organizers
- Pencils
- Markers & Highlighters
- Filing Products
- Art Supplies
- Easels
- Badge Holder & Accessories
- Office Paper
- Printer Supplies
- Book Covers
- Other Office & School Supplies
- Stationery Set
- Boards
- Clipboards
- Stamps
- Drafting Supplies
- Stencils
- Electronic Dictionary
- Books
- Map
- Magazines
- Calculators
- Baby & Toddler Toys
- Educational Toys
- Classic Toys
- Dress Up & Pretend Play
- Toy Vehicle
- Stuffed Animals & Plush Toys
- Outdoor Toys & Structures
- Balloons & Accessories
- Baby Food
- Children's Clothing
- Baby Supplies & Products
- Maternity Clothes
- Kids Shoes
- Baby Care
- Novelty & Gag Toys
- Dolls & Accessories
- Puzzle & Games
- Blocks & Model Building Toys
- Toddler Clothing
- Baby Clothing
- Kids' Luggage & Bags
- Arts, Crafts & DIY Toys
- Action & Toy Figures
- Baby Appliances
- Hobbies & Models
- Remote Control Toys
- Promotional Toys
- Pregnancy & Maternity
- Hygiene Products
- Kid's Textile&Bedding
- Novelty & Special Use
- Toy Weapons
- Baby Gifts
- Baby Storage & Organization
- Auto Drive Systems
- ATV/UTV Parts & Accessories
- Marine Parts & Accessories
- Other Auto Parts
- Trailer Parts & Accessories
- Auto Transmission Systems
- Train Parts & Accessories
- Universal Parts
- Railway Parts & Accessories
- Auto Brake Systems
- Aviation Parts & Accessories
- Truck Parts & Accessories
- Auto Suspension Systems
- Auto Lighting Systems
- New Energy Vehicle Parts & Accessories
- Auto Steering Systems
- Wheels, Tires & Accessories
- Bus Parts & Accessories
- Auto Performance Parts
- Cooling System
- Go-Kart & Kart Racer Parts & Accessories
- Air Conditioning Systems
- Heavy Duty Vehicle Parts & Accessories
- Auto Electrical Systems
- Auto Body Systems
- Auto Engine Systems
- Container Parts & Accessories
- Motorcycle Parts & Accessories
- Refrigeration & Heat Exchange Equipment
- Machine Tool Equipment
- Food & Beverage Machinery
- Agricultural Machinery & Equipment
- Apparel & Textile Machinery
- Chemical Machinery
- Packaging Machines
- Paper Production Machinery
- Plastic & Rubber Processing Machinery
- Industrial Robots
- Electronic Products Machinery
- Metal & Metallurgy Machinery
- Woodworking Machinery
- Home Product Manufacturing Machinery
- Machinery Accessories
- Environmental Machinery
- Machinery Service
- Electrical Equipment Manufacturing Machinery
- Industrial Compressors & Parts
- Tobacco & Cigarette Machinery
- Production Line
- Used Industrial Machinery
- Electronics Production Machinery
- Other Machinery & Industrial Equipment
- Camera, Photo & Accessories
- Portable Audio, Video & Accessories
- Television, Home Audio, Video & Accessories
- Video Games & Accessories
- Mobile Phone & Accessories
- Electronic Publications
- Earphone & Headphone & Accessories
- Speakers & Accessories
- Smart Electronics
- TV Receivers & Accessories
- Mobile Phone & Computer Repair Parts
- Chargers, Batteries & Power Supplies
- Used Electronics
- VR, AR, MR Hardware & Software
- Projectors & Presentation Equipments
- Other Consumer Electronics
- Cables & Commonly Used Accessories
- Computer Hardware & Software
- Displays, Signage and Optoelectronics
- Discrete Semiconductors
- Wireless & IoT Module and Products
- Telecommunications
- Connectors, Terminals & Accessories
- Development Boards, Electronic Modules and Kits
- Circuit Protection
- Sensors
- Isolators
- Audio Components and Products
- Integrated Circuits
- Power Supplies
- Relays
- RF, Microwave and RFID
- Electronic Accessories & Supplies
- Passive Components
- PCB & PCBA
- Air Quality Appliances
- Home Appliance Parts
- Heating & Cooling Appliances
- Small Kitchen Appliances
- Laundry Appliances
- Water Heaters
- Water Treatment Appliances
- Refrigerators & Freezers
- Personal Care & Beauty Appliances
- Major Kitchen Appliances
- Cleaning Appliances
- Second-hand Appliances
- Smart Home Appliances
- Other Home Appliances
- Energy Chemicals
- Inorganic Chemicals
- Basic Organic Chemicals
- Agrochemicals
- Admixture & Additives
- Catalysts & Chemical Auxiliary Agents
- Pigments & Dyestuff
- Coating & Paint
- Daily Chemicals
- Polymer
- Organic Intermediate
- Adhesives & Sealants
- Chemical Waste
- Biological Chemical Products
- Surface Treatment Chemicals
- Painting & Coating
- Chemical Reagents
- Flavor & Fragrance
- Non-Explosive Demolition Agents
- Other Chemicals
- Custom Chemical Services
Is Trade Credit Insurance Available for Architectural Aluminium Profile Purchases?
Trade credit insurance could help manage certain risks associated with purchasing architectural aluminium profiles, but the available information does not verify that Xinhe Aluminium provides such insurance or that a specific order is covered. Before production or payment, buyers should obtain written confirmation from the insurer covering the transaction and its applicable conditions.
Key Findings for Buyers
- The supplier information does not confirm an active trade credit insurance policy, coverage limit, or insured transaction.
- Xinhe Aluminium states that it provides integrated production, distribution, and direct sales, with a 3-ton MOQ for aluminium profiles and an estimated delivery period of 15–20 days.
- Its quality-control process includes 100% production-line inspection, laboratory sampling and testing, and inspection of incoming raw materials.
- Architectural profile solutions are listed for curtain walls, sliding doors, and sliding windows used in hotels, homes, offices, commercial buildings, and other construction projects.
How to Assess the Purchase Risk
Trade credit insurance is an independent risk-management arrangement and should not be confused with the terms of an aluminium profile sales contract. The supplier information describes payment options, delivery arrangements, product inspections, and after-sales service, but it does not state that architectural profile orders are automatically insured by Xinhe Aluminium.
Buyers should ask the insurer to confirm the insured parties, approved supplier and buyer relationship, covered order value, payment conditions, waiting period, exclusions, claim procedures, and required evidence. These points determine whether the policy protects against the specific financial exposure created by the purchase.
Xinhe Aluminium lists T/T and sight L/C among its payment methods. For aluminium profiles, the stated T/T structure is 30% D/P before production and 70% paid before loading. For aluminium windows and doors, the stated arrangement is 50% D/P before manufacturing, with the remaining balance due before loading. These terms explain how payment is settled and should not be treated as proof of trade credit insurance.
Product, Quality, and Delivery Information
The supplier reports several inspection stages, including full inspection on the production line, laboratory sampling and testing, and checks on incoming raw materials. Listed credentials include the SIRIM certificate for aluminium and aluminium alloy extruded shapes used in windows and sliding doors, as well as the CNAS Laboratory Accreditation Certificate, No. CNAS L 10434, for its nationally accredited laboratory.
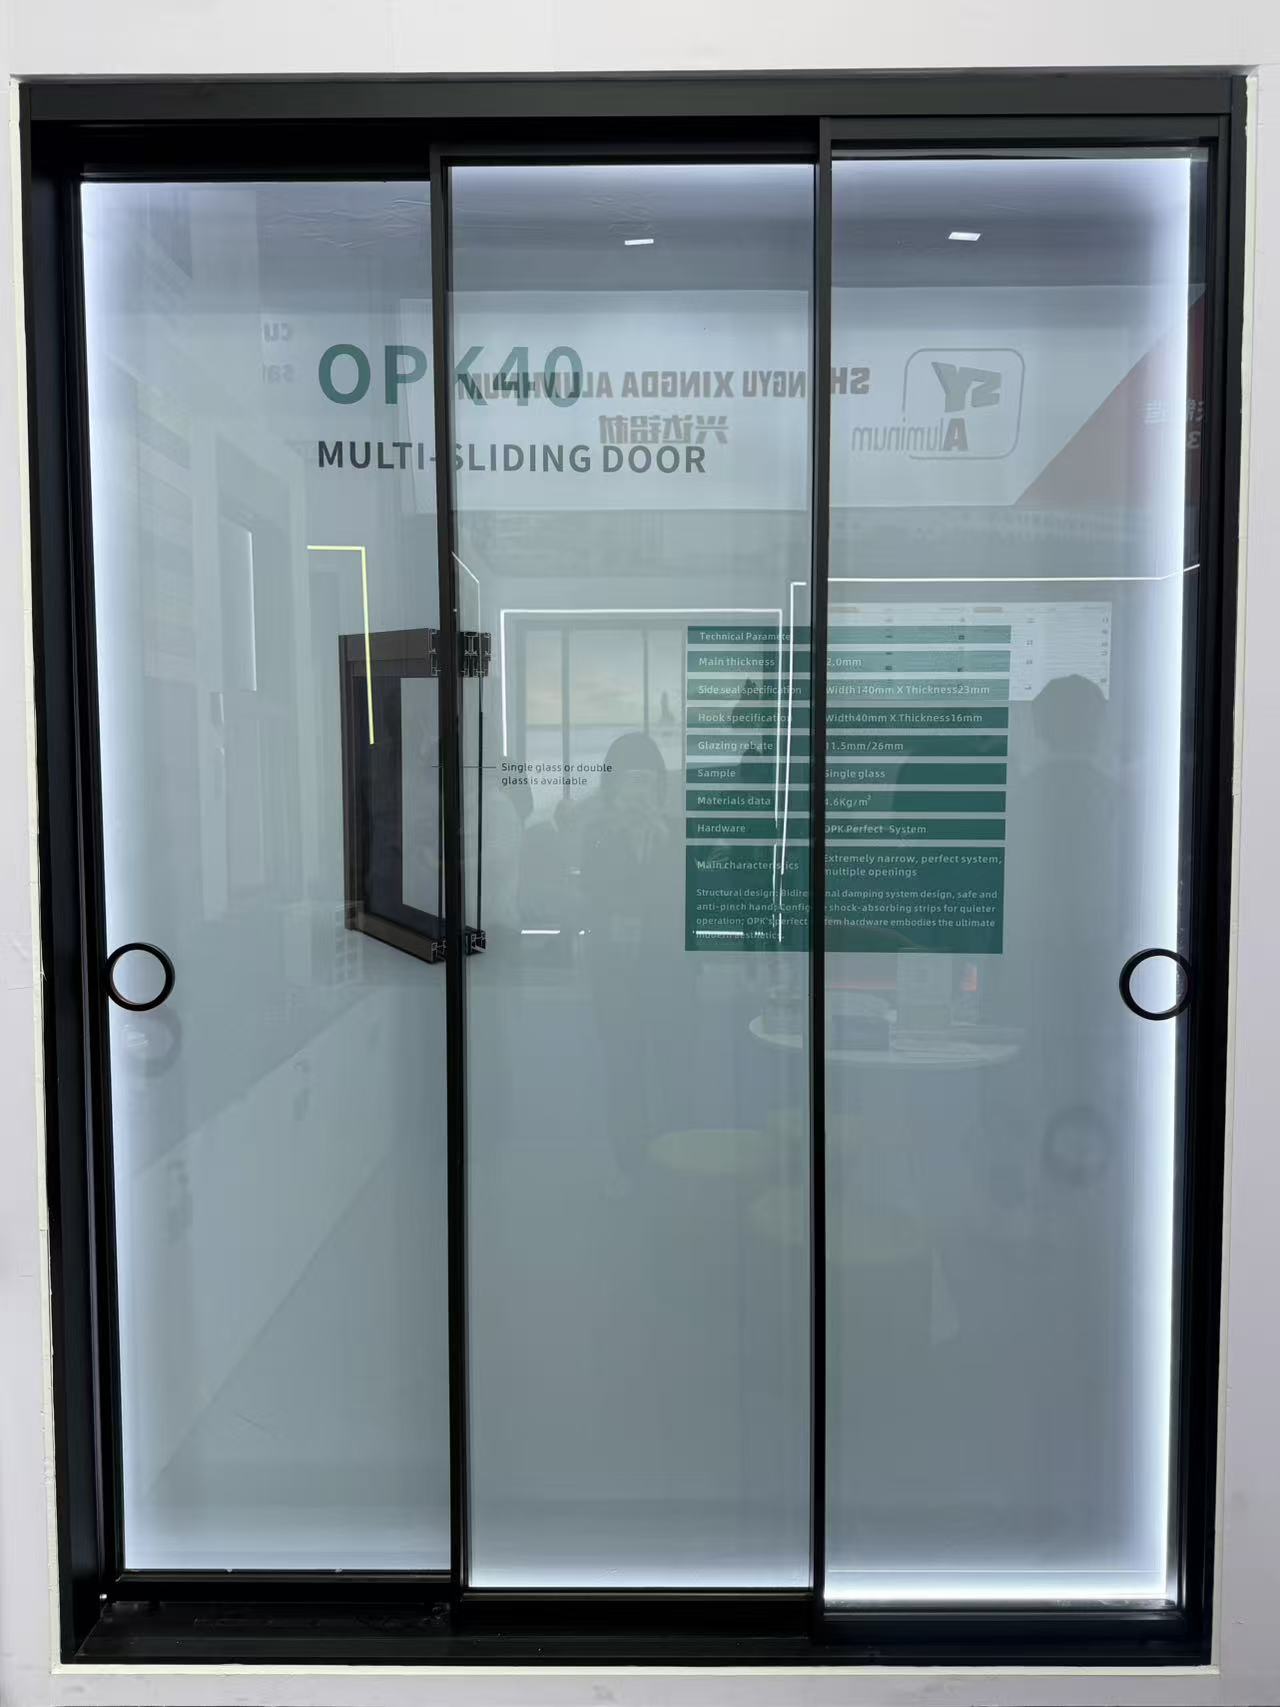
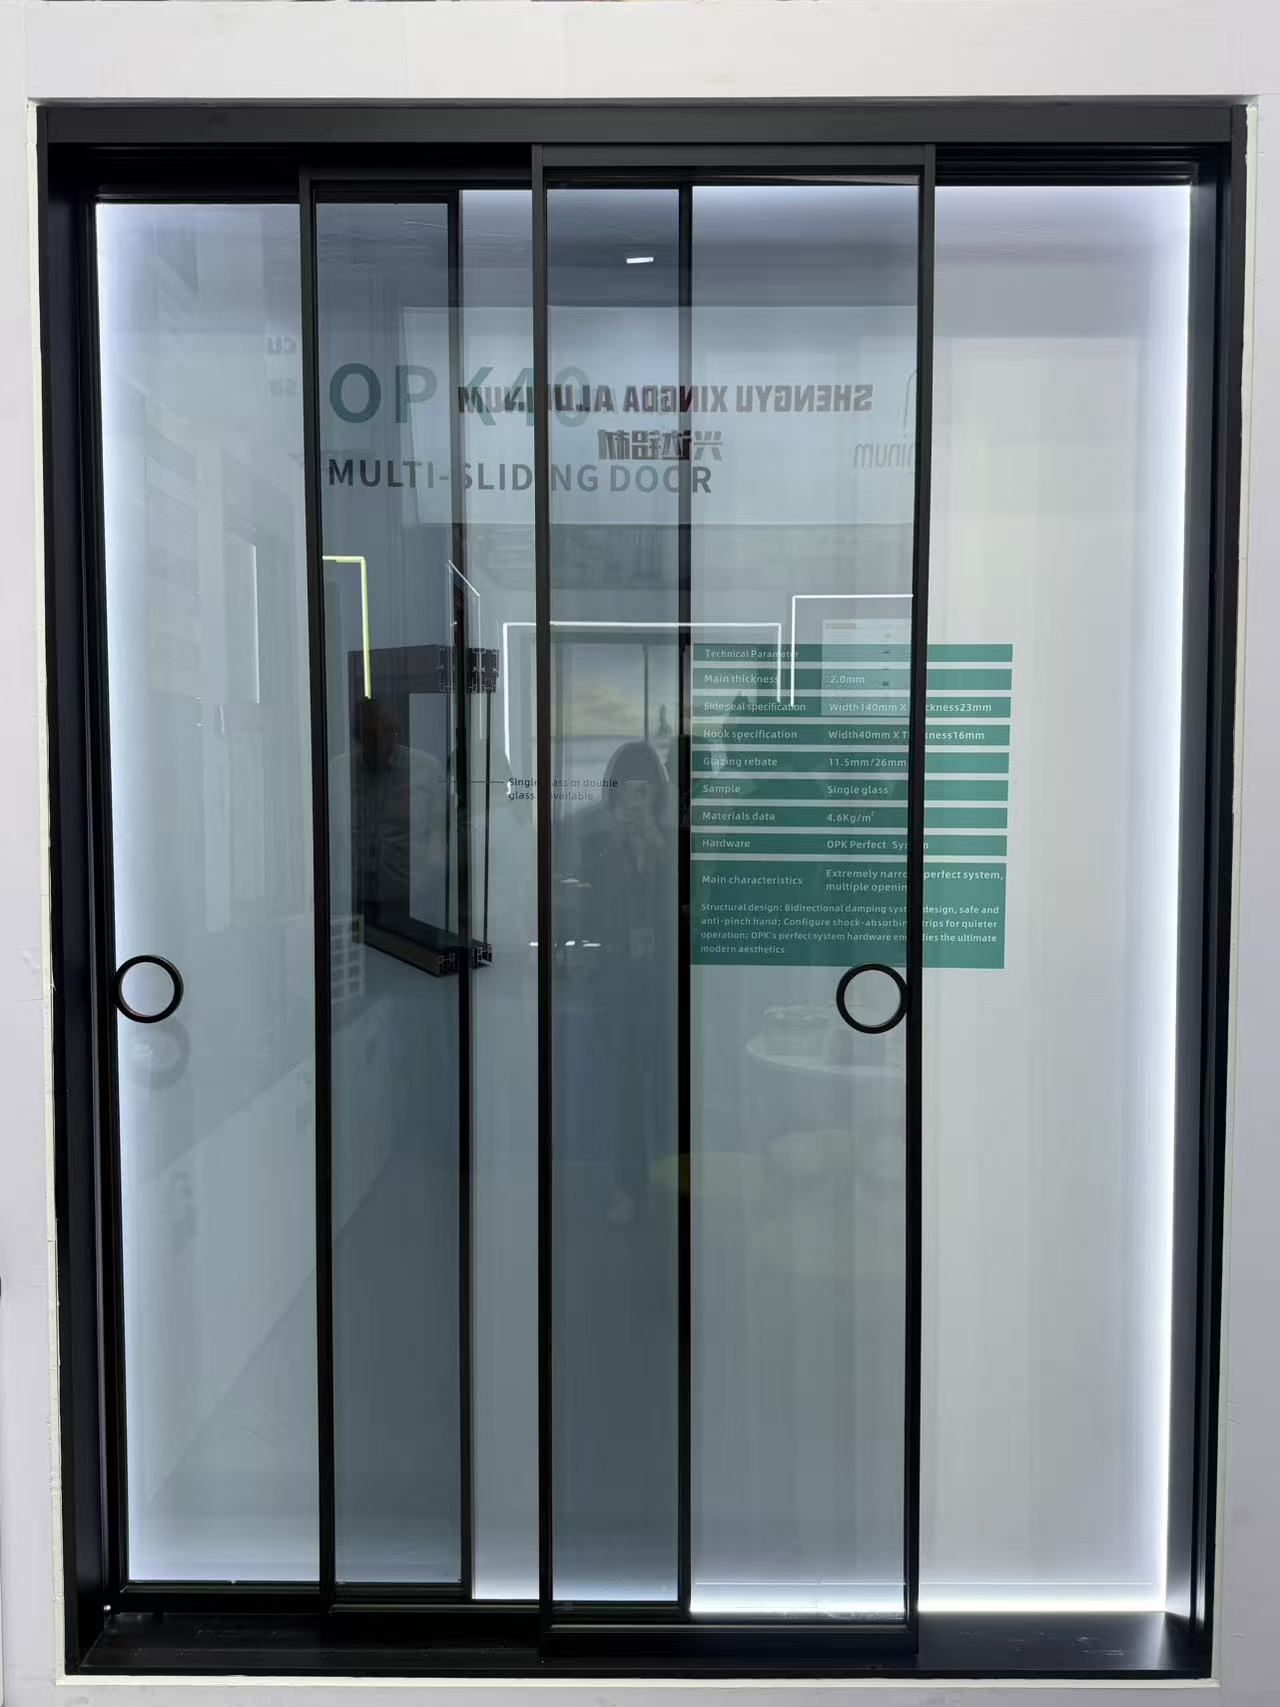
The featured Sliding Door product is described with a 2.0 mm main thickness, a 140 mm width by 23 mm thickness side specification, and a 40 mm width by 16 mm thickness hook specification. It also lists 11.5 mm and 26 mm glazing rebates, material data of 4.6 kg/m², OPK Perfect System hardware, and several opening configurations. These details help define the goods being ordered, while insurance eligibility must be assessed separately.
Reported cooperation projects include hotels, offices, residences, and other building developments in multiple markets. Feedback from these projects refers to delivery coordination, packaging, profile wall thickness, custom mould development for special cross-sections, and responses to production or sales issues. Such information indicates stated project experience, but it does not establish that any purchase is protected by trade credit insurance.
Risk-Control Comparison
| Risk category | Information provided by the supplier | Questions for the insurer |
|---|---|---|
| Payment exposure | T/T and sight L/C payment options are available | Does the policy cover non-payment, delayed payment, or another defined credit event? |
| Product quality | Production-line inspection, laboratory testing, and incoming material checks are stated | Are defective goods, quality disputes, or related losses included or excluded? |
| Delivery performance | The stated lead time is 15–20 days, and sea freight is available | Does coverage extend to delay, non-delivery, or resulting financial losses? |
| Order requirements | The aluminium profile MOQ is 3 tons; the featured Sliding Door MOQ is 500 sqm | Does the order value, product type, and payment structure satisfy policy conditions? |
| Post-sale obligations | A comprehensive after-sales service system is reported | Are service disputes and performance-related claims covered? |
Buyer Checklist Before Ordering
Confirm the insurance arrangement
Request an insurer-issued confirmation identifying the covered parties, transaction amount, approved credit terms, exclusions, claim deadline, and documentation requirements. Do not assume that an insurance policy applies merely because the supplier supports an L/C or provides inspection records.
Match the contract and product details
For the Sliding Door product, verify the 500 sqm MOQ, technical dimensions, hardware configuration, glazing rebates, delivery schedule, inspection standard, shipping method, and after-sales responsibilities. Ensure that the sales contract and insurance documents use consistent descriptions and values.
Frequently Asked Questions
Does the available supplier information prove that an architectural profile order is insured?
No. It confirms payment options, production controls, shipping information, and after-sales support, but it does not identify a trade credit insurance policy or confirm coverage for a buyer's order.
Does a sight L/C provide the same protection as trade credit insurance?
No. A sight L/C is a listed payment method whose protection depends on the issuing bank, documentary conditions, and the agreed contract. The available information does not connect the L/C option with trade credit insurance.
What should be reviewed when purchasing the Sliding Door product?
Review the product specifications, 500 sqm MOQ, 15–20 day delivery estimate, inspection process, payment arrangement, freight method, and after-sales terms. Separately obtain written insurance confirmation covering the relevant commercial risks.
Conclusion
Trade credit insurance may be appropriate for an architectural aluminium profile purchase, but its availability and scope cannot be confirmed from the supplied data. Buyers should secure written insurer approval before production or payment and ensure that the policy matches the purchase contract, payment terms, delivery obligations, inspection requirements, and claim process. Xinhe Aluminium states that it offers integrated production, distribution, and direct sales, together with quality inspections, T/T and sight L/C options, and sea freight services. For technical assistance or project support, contact xh@xinhealuminium.com.
About Xinhe Aluminium
Guangdong Xinhe Aluminium Co., Ltd specializes in the research, development, and manufacture of building, decorative, and industrial aluminium alloy profiles. The company describes its R&D and testing laboratory as a CNAS national accredited facility. Established in 1998, it reports annual production of 200,000 tons and serves customers in the Philippines, Malaysia, Singapore, Japan, South Korea, Vietnam, India, South Africa, Australia, Europe, Russia, Kazakhstan, and other markets. Its listed certifications include SIRIM and ISO 9001:2015, while its project experience includes hotel, office, residential, and building applications.
REPORT